“Must be nice having money while your family struggles,” my sister sneered after demanding another $12,000. When I refused, Dad slammed his glass down. “Help her or don’t bother coming home.” I walked out, took a job 1,600 miles away, and stopped every payment I’d been making for her. By sunrise, I had 41 missed calls. I thought they were just furious about losing my financial support. But 3 days later, my bank flagged $4,219.87 in charges I’d never authorized. When I called to investigate, the representative said something that made my blood run cold…
My name is Callum Reed. I’m 34, and for most of my adult life, I was the responsible child.
I worked through college, built a career in financial systems, and saved carefully.
My younger sister, Brenna, was the opposite.
At 25, she quit her job to open a floral design business. She rented an expensive storefront, purchased custom furniture, and spent thousands creating the appearance of success.
For a while, business was good.
Then orders declined, expenses piled up, and Brenna started calling me.
First, she needed $3,000 for rent.
Then $1,500 for equipment repairs.
Then another $2,200 for suppliers.
Over several years, I’d given or loaned her more than $20,000.
Some amounts were birthday gifts or help I never expected back. But most were loans she’d promised to repay.
Every time I hesitated, my parents reminded me that family came first.
My father, Patrick, was especially persistent.
“She’s your only sister, Callum. You can’t abandon her.”
But every emergency seemed to arrive shortly after Brenna bought something she couldn’t afford.
Eventually, I’d had enough.
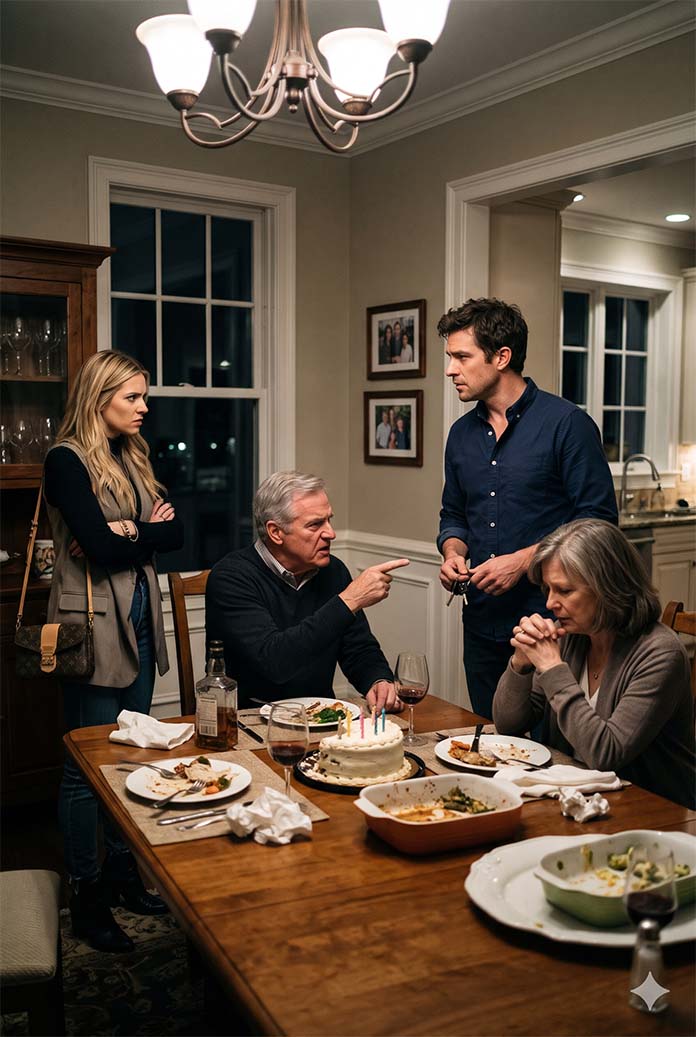
The breaking point came at Dad’s 66th birthday dinner.
Brenna arrived 45 minutes late, carrying an expensive handbag and complaining about her struggling business.
Then she looked directly at me.
“Must be nice having money while your family struggles.”
I put down my fork.
“I gave you $2,500 last month.”
“And? That barely covered anything.”
“Then you need to reduce your expenses.”
She laughed.
“Of course you’d say that. You think you’re better than everyone because you have a good job.”
Mom stared at her plate.
Dad cleared his throat.
“Callum, your sister needs $12,000 to keep her business operating. You can afford to help.”
I stared at him.
“$12,000?”
“Just until she gets through the upcoming wedding season.”
I’d heard promises like that too many times.
“No.”
Brenna’s smile disappeared.
“Excuse me?”
“I’m your brother, Brenna. I’m not your bank.”
Dad slammed his glass down.
“You apologize to your sister.”
“For what? Refusing to finance another disaster?”
His face hardened.
“If you walk out while your sister needs help, don’t expect this family to welcome you back.”
I looked at Mom.
She said nothing.
That silence hurt more than the argument.
I stood, picked up my jacket, and walked out.
What my family didn’t know was that I’d already received a formal job offer in Denver.
Mom knew I’d been interviewing with a company there. I’d mentioned it weeks earlier, hoping she might be happy for me.
Apparently, she’d told Dad.
But nobody knew the company had offered me a senior position with a higher salary and relocation assistance.
I’d hesitated to accept because I didn’t want to leave my parents.
That night, sitting alone in my apartment, I finally signed the offer.
Shortly afterward, my phone vibrated.
Dad.
Help her or don’t bother coming home.
I replied:
I’m not paying another bill for Brenna. If that’s your decision, I accept it.
Then I canceled the recurring payments I’d been making on her behalf, removed her saved bank details, and changed my passwords.
I put my phone on Do Not Disturb.
By sunrise, I had 41 missed calls.
Dad. Mom. Brenna.
Some messages were angry.
Others begged me to reconsider.
Not 1 asked whether I was okay.
For the next 3 days, I ignored them and focused on my move.
Then, on Tuesday afternoon, 3 banking notifications appeared.
$1,284.67 — floral supplier.
$739.20 — overdue business utilities.
$2,196.00 — commercial rent payment.
I hadn’t authorized any of them.
I immediately called my credit card issuer.
After reviewing the transactions, the representative said, “Mr. Reed, these purchases were made using a card issued to an authorized user.”
My stomach tightened.
“What authorized user?”
“Helena Reed.”
My mother.
4 years earlier, Mom had undergone knee surgery. I’d added her as an authorized user to help with medical expenses while she recovered.
I’d forgotten the card existed.
Apparently, she hadn’t.
I asked the representative to block further purchases, remove Mom’s authorized access, and investigate the transactions.
She explained that because I’d originally authorized the additional card, I might still be responsible for the charges, even though I hadn’t agreed to those particular purchases.
After hanging up, I called Mom.
She answered immediately.
“Callum, thank goodness—”
“Did you give Brenna my credit card?”
Silence.
“Mom?”
Her voice broke.
“Your father said you’d eventually agree to help.”
I closed my eyes.
“So you gave her my card after I explicitly said no?”
“He said it was only temporary. He said if the shop survived another few months, everything would be fine.”
“That’s not an answer.”
She began crying.
Then she whispered something unexpected.
“Callum, there’s something you need to know about your father’s finances.”
Mom arrived at my apartment that evening carrying a thick envelope.
Inside were overdue notices, loan statements, and business invoices.
“Your father borrowed $68,000 against the house,” she said.
I stared at her.
Our childhood home had been paid off for years.
Dad had opened a home-equity line of credit secured against the property, which was titled in his name.
Initially, he’d withdrawn $15,000 to help Brenna launch her business.
Mom knew about that.
What she hadn’t realized was that Dad had continued drawing from the credit line whenever Brenna needed more money.
By the time she discovered the latest statements, the outstanding balance had reached nearly $68,000.
And Dad had already missed 2 payments.
“The $12,000 wasn’t going to pay off the loan,” Mom explained. “Your father wanted to keep Brenna’s shop open through the wedding season. He thought if business improved, she’d finally earn enough to start paying him back.”
I stared at the paperwork.
“So he risked the house, exhausted his savings, and decided I should rescue everyone?”
Mom lowered her head.
“Yes.”
“Why didn’t you tell me?”
“I only found out how bad things were a few weeks ago. Your father told me he’d handle it. I wanted to believe him.”
She wiped her eyes.
“Then he pressured me to give Brenna your card. I was terrified we’d lose the house, and I convinced myself you’d forgive us.”
She swallowed.
“But when you called about the charges, I realized we’d dragged you into debts you never agreed to. I couldn’t keep defending him.”
I was still processing her confession when she pulled a small notebook from the envelope.
“There’s something else.”
I almost laughed.
“What could possibly be worse?”
She opened the notebook.
“Your father has been collecting repayments from Brenna that were supposed to go to you.”
I froze.
“What?”
“When Brenna’s business was doing better, she started making monthly payments. Your father told her he was handling the old loans between you.”
I stared at her.
“How much?”
“I’ve found more than $5,000 in his records.”
For months, Dad had been accepting payments from Brenna while telling me she hadn’t repaid a cent.
He’d used the money toward his credit line and household expenses.
Mom had discovered the transfers in a ledger he kept with his financial documents.
I couldn’t believe it.
Dad had pressured me to forgive Brenna’s debts while secretly keeping money she intended to repay.
And he’d made sure neither of us knew what the other was doing.
That evening, I called Brenna.
She answered angrily.
“Are you finally ready to help?”
“I know about Dad’s credit line. And I know you’ve been sending him money meant for me.”
Silence.
Then she whispered, “Mom told you?”
“Have you really been repaying me?”
“Yes! Dad said you were tired of talking to me about the old loans. He told me to send the payments to him, and he’d pass them on.”
“Then why didn’t you ever mention it?”
“He said bringing up those repayments whenever I needed more help would only start another argument. He told me he’d keep track of everything.”
She paused.
“When you said I never paid you back, I thought you meant I kept borrowing more than I was repaying. I didn’t realize Dad wasn’t giving you anything.”
My chest tightened.
Within minutes, she sent screenshots of bank transfers.
$400.
$250.
$600.
Every payment went to Dad.
Several were labeled For Callum or Loan repayment.
We reviewed the records together and confirmed that Dad had received exactly $5,600 intended for me.
Then Brenna revealed something even worse.
“Dad said you’d eventually help with the house loan once you accepted that job out west.”
My blood ran cold.
“What?”
“He knew you were interviewing in Denver. He kept saying the higher salary and relocation money would make $12,000 easy for you.”
I hadn’t even accepted the position when Dad began planning how to spend the money.
“He told me not to worry about your refusal at dinner,” Brenna continued. “He said you’d calm down and come around.”
I closed my eyes.
Dad had been making promises using money that wasn’t his.
And when I refused, he’d threatened to disown me.
“Brenna,” I said quietly, “Dad has been lying to both of us.”
She began crying.
For the first time, she didn’t blame me.
We met the following morning at a coffee shop.
I brought my spreadsheet documenting the loans I’d given her.
She brought her bank statements.
When she saw how much she still owed, her face went pale.
“I didn’t realize it was that much.”
“You never wanted to look at the numbers.”
She lowered her head.
“You’re right.”
I explained that the $5,600 she’d already paid Dad would count toward her debt. She wouldn’t be required to repay the same money twice.
Dad was responsible for returning those funds to me.
But Brenna still owed the remaining loan balance and the $4,219.87 she’d charged to my card.
“I can’t pay all of that now,” she whispered.
“I know.”
“Then what do you want me to do?”
“Stop borrowing. Close the shop if it can’t survive. Find steady work. And make a realistic repayment plan.”
She wiped her eyes.
“I feel like such a failure.”
“Failing at a business doesn’t make you a failure, Brenna. But expecting everyone else to sacrifice their future to keep it alive isn’t fair.”
She stared at the table.
Then she nodded.
“I know.”
For once, I believed she understood.
But I wasn’t going to give her another dollar based on promises alone.
That Sunday, Brenna and I confronted Dad together.
Mom was there.
I placed the credit line statements and repayment records on the coffee table.
“We know everything,” I said.
Dad’s face hardened.
“I did what I had to do for this family.”
“You borrowed nearly $68,000 without telling us how bad things had become,” Brenna said.
“And you kept $5,600 I sent you for Callum.”
Dad looked between us.
“I used that money to keep this house from going under.”
“Then why didn’t you tell us?” I asked.
“Because neither of you understands what I’ve sacrificed!”
He pointed at Brenna.
“Your business would’ve closed without me.”
Then he turned toward me.
“And you wouldn’t have your comfortable life if I hadn’t raised you properly.”
I stood.
“You chose to borrow that money. Brenna chose to keep spending. Neither decision was mine.”
His face reddened.
“I put a roof over your head for 18 years!”
“Because you were my father, not because I signed a contract to finance the rest of your life.”
The room fell silent.
Dad pointed toward the door.
“Get out. And don’t expect a penny of inheritance!”
I looked around the house he was now struggling to keep.
There was something painfully ironic about threatening me with an inheritance while facing financial disaster.
“Keep whatever you have left, Dad.”
I picked up my jacket.
“I’d rather build a future you can’t threaten to take away.”
This time, Brenna followed me out.
I moved to Denver 3 weeks later.
Starting over wasn’t easy, but for the first time in years, my paycheck belonged entirely to me.
Brenna closed her floral shop, sold the remaining inventory and equipment, and accepted a full-time administrative position at a medical office.
She signed a written repayment agreement covering what she still owed, including the credit card purchases. The $5,600 she’d already sent Dad was credited against her original loans.
I remained responsible for the card account while resolving the matter with the issuer, but Brenna began reimbursing me through scheduled payments.
Mom admitted her role in giving away the card and offered to help cover the charges. I told her that rebuilding my trust mattered more than another promise involving money.
She agreed never to give anyone access to my finances again.
After consulting an attorney and a financial adviser, Mom moved temporarily into her sister’s guest room.
Dad refused to sell the house.
He insisted Brenna’s business would somehow recover, even though she’d already closed it.
Then the lender sent another warning.
His savings were nearly gone, the payments were overdue, and nobody was willing to rescue him.
Finally, he listed the property.
The house remained on the market for several weeks before a buyer made an offer.
After the sale closed, Dad used the proceeds to pay off the home-equity debt and the selling costs.
There was enough equity left for him to move into a modest rental and return the $5,600 he’d intercepted from Brenna’s repayments.
The transfer arrived without warning.
The message attached was brief.
This money should have been yours from the beginning.
I didn’t reply.
Several weeks later, a handwritten letter arrived from Dad.
I nearly threw it away.
Instead, I opened it.
He wrote about losing the house he’d expected to live in for the rest of his life.
About watching Mom move out.
About realizing Brenna had finally found steady work without relying on him.
And about the uncomfortable silence of living alone in a small rental apartment.
For years, he’d convinced himself he was protecting the family by solving everyone’s problems.
When the debts became overwhelming, he’d been too ashamed to admit his mistakes.
Instead, he’d turned to me because I had always been the responsible one.
Then I reached a sentence that made me stop.
I kept expecting you to fix everything because you always had. When you finally refused, I blamed you rather than admit what I’d done.
Below it, he’d written:
I made you believe your place in this family depended on what you could provide. I was wrong.
I read those words twice.
It wasn’t a perfect apology.
A letter couldn’t erase years of manipulation.
But losing the house, his wife’s trust, and the unquestioning loyalty of his children had finally forced Dad to confront consequences he couldn’t pass to someone else.
I folded the letter and placed it in a drawer.
I wasn’t ready to forgive everything.
But I wasn’t closing the door forever.
6 months after moving, Brenna called me one Friday evening.
“Hey,” she said. “Check your bank account.”
A $250 transfer had arrived.
“That’s your monthly payment.”
“I see it.”
“And I got promoted.”
I smiled.
“Congratulations.”
She hesitated.
“Callum, I know paying you back doesn’t erase what I did.”
“No. It doesn’t.”
“But I’m trying.”
“I can see that.”
Her voice softened.
“I miss having a brother who trusts me.”
I looked out my apartment window toward the mountains.
“Trust takes time, Brenna.”
“I know.”
“But we can keep working on it.”
She started crying.
This time, I didn’t feel pressured to solve anything.
I simply listened.
Nearly a year after that birthday dinner, my life looks completely different.
Brenna still makes monthly payments.
Mom has her own apartment and manages her finances independently.
Dad and I exchange occasional messages. Our relationship remains distant, but he no longer asks me for money.
Last week, he called unexpectedly.
We talked about my work and the weather.
Then he said, “Your sister tells me you’re doing well.”
“I am.”
He paused.
“Must be nice having everything figured out.”
For a moment, I remembered Brenna saying almost those exact words at his birthday dinner.
But this time, they didn’t hurt.
“Dad, I don’t have everything figured out.”
He stayed quiet.
“I still make mistakes. I still have bills and responsibilities. The difference is that I’ve stopped taking responsibility for everyone else’s decisions.”
There was a long silence.
Then he said softly, “I suppose that’s fair.”
After we hung up, I sat quietly in my apartment.
For years, I’d believed that being a good son meant sacrificing whatever was necessary to keep my family happy.
I thought saying no made me selfish.
I thought boundaries meant abandonment.
And I thought love had to be proven through money.
Now I understand something I wish I’d learned much earlier.
Helping someone doesn’t mean financing their mistakes forever.
Forgiving someone doesn’t mean trusting them immediately.
And loving your family doesn’t mean allowing them to destroy the future you’ve worked so hard to build.
The day my father told me not to come home, I thought I’d lost my family.
Instead, I discovered who we were when money stopped holding us together.
We haven’t fixed everything.
Maybe we never will.
But my sister is learning responsibility. My mother is learning to speak up. My father is learning that love doesn’t give him the right to control people.
And me?
I’m finally learning that I matter even when I have nothing to give.
I didn’t abandon my family when I stopped paying their bills. I simply stopped abandoning myself.