FOR SIX YEARS, MY HUSBAND TOOK MY ENTIRE PAYCHECK AND RATIONED ME TWENTY DOLLARS A DAY FOR GROCERIES—UNTIL OUR DAUGHTER ASKED WHY I HAD TO BEG HIM FOR FOOD, AND I DECIDED TO STOP PAYING FOR HIS LIFE.
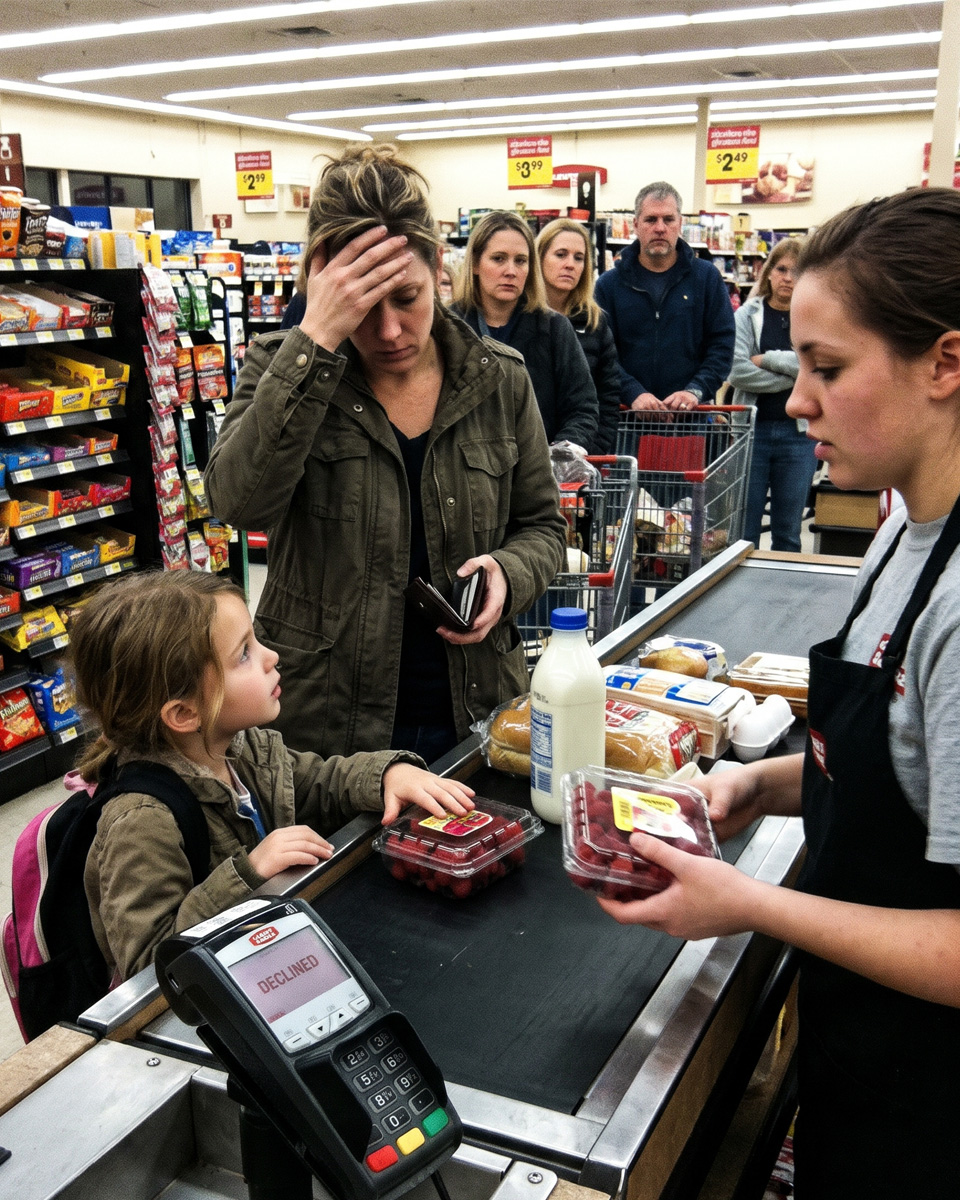
I am thirty-four years old, a high school biology teacher, and for six years I lived inside an immaculate, two-story colonial in suburban Cleveland that felt increasingly like an open-air prison.
My husband, Arthur, is a senior portfolio manager at a boutique investment firm downtown, the kind of man whose hair is always parted on the left and whose emotional range is entirely captured in quarterly returns.
When we bought our house in 2020, staring down an astronomical mortgage and the prospect of raising two children, Arthur delivered an hour-long slide presentation in our living room outlining the necessity of consolidated financial command.
He argued that with his institutional investment background and my admitted indifference to equity markets, pooling our money under his single authority was the only mathematically rational path to generational wealth.
I trusted him implicitly, surrendered my paychecks, and lived on whatever crumbs he budgeted back to me.
Every month, my four-thousand-dollar teacher’s salary landed via direct deposit into Arthur’s sole checking account, after which he left me precisely two hundred dollars for personal incidentals and fifty dollars every other day for groceries.
In 2020, fifty dollars at an Ohio supermarket could feed a small household for two days if you were smart about pantry staples and bulk purchasing.
By 2026, fifty dollars at Giant Eagle barely covered two gallons of organic milk, a dozen cage-free eggs, a loaf of sourdough, and a small package of chicken cutlets.
Our son, Leo, had just turned six, while our eight-year-old daughter, Chloe, was growing so fast that her ankles constantly showed beneath her denim jeans.
Feeding them meant spending every evening running mathematical permutations in the produce aisle, discreetly swapping out flank steak for bruised squash, and hiding generic labels inside empty branded cereal boxes so the kids wouldn’t feel deprived.
Whenever I politely requested twenty more dollars a week to accommodate basic food inflation, Arthur would lean back against the marble island, swirl his single-malt scotch, and tell me that fiscal incompetence was a personal choice rather than a macroeconomic condition.
The silent humiliation crystallized last month when my widowed mother took a bad fall down her basement stairs outside Pittsburgh and fractured her femoral neck.
Her Medicare plan covered the immediate surgery, but the outpatient physical rehabilitation clinic demanded an upfront co-pay of twelve hundred dollars before admissions would approve her intake paperwork.
I stood in the fluorescent-lit hospital corridor, listening to the monitor beeping through my mother’s half-open door, and dialed Arthur with tears burning behind my eyes.
He listened to my frantic explanation, paused long enough for me to hear the click-clack of his mechanical keyboard, and flatly declined to transfer the full amount.
“I can authorize four hundred dollars from the discretionary pool, Rachel, but not a cent more,” he said, his voice as sterile as a probate hearing.
“Your brother Mark earns a respectable living at the auto plant; expecting us to unilaterally subsidize your mother’s domestic carelessness is bad governance.”
I ended the call right there, walked out to the parking garage, and sat in my nine-year-old Honda Civic with my forehead pressed against the steering wheel, shivering with cold fury.
Two weeks later, the biology department at my school hosted a farewell reception for our chairwoman, a woman who had mentored me through my first terrifying years of classroom teaching.
The contribution was forty-five dollars for a prix-fixe family-style lunch at a local Italian trattoria on Main Street.
When I texted Arthur asking for the funds, he texted back a screenshot of our quarterly water utility statement with a cold message: “Unscheduled entertainment expenses remain frozen through the end of the fiscal month.”
I spent that lunch hour locked in my supply closet, grading freshman lab reports on cellular mitosis while chewing on a bag of vending-machine almonds I had paid for with loose quarters scavenged from my glove compartment.
The breaking point arrived the following Sunday afternoon in the baking aisle of our neighborhood grocery store.
Chloe had been working on a homemade dessert project and reached for a six-dollar plastic container of fresh organic raspberries.
When I tapped my little debit card against the card reader at checkout, the screen flashed an abrasive crimson refusal: “TRANSACTION DECLINED — INSUFFICIENT FUNDS.”
I was four dollars short because Arthur had arbitrarily shaved twenty dollars off my weekly allowance to offset an unexpected lawn-aeration charge.
The cashier, a teenage girl with braces, gave me a look of deep, crushing pity while the queue of Sunday shoppers behind me shifted their feet impatiently.
I had to pull the raspberries out of Chloe’s little hands and push them across the scanner to be voided.
Chloe looked up at me with large, unblinking eyes and said, loud enough for three surrounding shoppers to hear: “Mommy, you work at the high school all day, so why do you have to ask Daddy for permission to buy berries?”
The question hit me like a physical blow to the sternum, peeling away six years of self-delusion in a single, icy second.
That night, after putting the children to bed, I walked into Arthur’s study and placed a handwritten sheet of paper on his polished mahogany desk.
It laid out a standard fifty-fifty split: each of us would contribute sixty percent of our salaries to a joint operational account for the mortgage and household utilities, leaving the remaining forty percent in our respective personal checking accounts.
Arthur didn’t even look at the figures; he merely picked up the page, folded it into quarters, and tossed it into the wastebasket beside his leather chair.
“We have discussed this, Rachel,” he said without looking up from his dual monitors. “You have zero financial literacy, and dividing our capital simply invites lifestyle creep.”
“I am the fiduciary anchor of this family, and as long as we live under this roof, the system remains non-negotiable.”
I didn’t yell, I didn’t cry, and I didn’t slam the door; I simply smiled, nodded slowly, and walked upstairs to our bedroom.
The next morning at seven o’clock, instead of heading straight to my homeroom, I walked into the administrative building of the school district and handed the payroll director a certified direct deposit revision form.
Effective immediately, one hundred percent of my four-thousand-dollar monthly compensation was redirected into a brand-new checking account I had opened online that morning with a credit union Arthur had never heard of.
Next, I dialed our mortgage lender, our homeowner’s insurance agency, and the city water bureau, officially removing my name from any automated payment authorizations tied to Arthur’s primary account.
For six years, Arthur had been using the combined weight of my steady public-sector salary to comfortably clear our five-thousand-dollar monthly fixed obligations while keeping his own high-risk investment capital untouched.
The calendar rolled over to the first of the month, the traditional day our five-thousand-dollar mortgage payment automatically drafted from Arthur’s checking account.
At precisely nine-fifteen on a Tuesday morning, my phone lit up with four consecutive calls from Arthur while I was dissecting a preserved bullfrog with my sophomore honors class.
I let them ring out, completed my lecture on amphibian circulatory anatomy, and only checked my voicemail during my third-period planning break.
Arthur’s voice was stripped of all its usual boardroom composure, cracking with panic and rising anger: “Rachel, where is your direct deposit? The mortgage auto-debit bounced an hour ago, my overdraft fees are compounding, and the bank is threatening to trigger a penalty rate. Transfer the money immediately.”
I didn’t call him back; instead, I sent a single text message: “My money is sitting securely in my personal account. As you noted, I lack macroeconomic discipline, so I am preserving my capital to prevent lifestyle creep.”
Thirty minutes later, Arthur’s Mercedes pulled into the school faculty parking lot with an aggressive screech of high-performance tires.
He strode into the front office demanding to see me, his tie loose, his suit jacket wrinkled, and his face mottled with purple indignation.
The school principal, an imposing former marine who had known me for a decade, barred Arthur at the reception desk and informed him that unannounced visitors were strictly forbidden beyond the administrative perimeter.
I stepped into the glass-walled conference room, closed the door behind us, and watched my husband pace back and forth like a trapped predatory animal.
“Are you insane?” he hissed, keeping his voice down through clenched teeth. “You are jeopardizing our credit score! Do you have any idea what an uncured mortgage default does to my underwriting profile at the firm?”
“I don’t particularly care about your underwriting profile, Arthur,” I replied, sitting down at the head of the conference table and folding my hands.
“What I care about is that my mother needed orthopedic care and had to beg her neighbors for help while you sat on hundreds of thousands of dollars of our joint surplus.”
“I care that my daughter had to watch her mother get humiliated in a grocery store over six dollars’ worth of fruit.”
Arthur sneered, stepping closer and leaning his knuckles against the conference table.
“You think you’re being clever, Rachel, but you don’t hold any cards here. I earn two hundred and ten thousand dollars a year; you make forty-eight thousand. You need my income to keep that house, feed those children, and maintain this lifestyle. If you don’t transfer your salary by five o’clock, I will freeze every credit card in your name and cut off the household utilities.”
That was when the real trap sprang shut.
Two days earlier, while Arthur was at his weekend tennis club, I had pulled our physical filing cabinets apart and downloaded our joint tax filings for the preceding four years from the IRS portal.
Arthur had been filing our federal returns under the status of Married Filing Jointly, which meant I had absolute, unrestricted legal entitlement to view every W-2, every 1099, and every brokerage disbursement statement.
What I found was not a masterclass in austere family preservation, but a textbook case of financial narcissism and staggering hypocrisy.
Arthur hadn’t been stockpiling cash for our children’s college 529 plans or our joint retirement; he had lost seventy-four thousand dollars two years ago day-trading speculative semiconductor options on an unapproved margin account.
To cover those catastrophic losses without exposing his failure to his partners, he had been using my predictable, guaranteed teacher paychecks to cover our base living costs while siphoning his quarterly bonuses into a private shell corporation registered under his brother’s name in Delaware.
Worse still, the credit-card statements linked to that private shell company showed recurring weekend expenditures that had nothing to do with market research: four-hundred-dollar dinners at steak houses, country club bar tabs, and custom golf club fittings.
He had been living like a high-rolling bachelor on his discretionary earnings while demanding that his wife stretch sixty cents’ worth of dried lentils into Tuesday dinner.
I reached into my canvas tote bag, pulled out a thick manila folder containing fifty pages of forensic accounting printouts, and slid it smoothly across the mahogany table.
“Before you threaten to cut off the water or freeze credit cards, Arthur, you should take a close look at pages twelve through twenty-four,” I whispered.
Arthur picked up the folder impatiently, his eyes scanning the first few lines before his entire posture froze solid.
The color drained from his face so fast it looked as though someone had pulled a drain plug at the base of his neck.
“Where… where did you get these?” he stammered, his fingers trembling against the heavy bond paper.
“From the IRS repository using my own Social Security number, which you so conveniently signed on line twenty-four of our joint Form 1040,” I said, leaning forward.
“And here is the reality of the situation, Arthur: Ohio is an equitable distribution state.”
“If I walk across the street to a domestic relations attorney this afternoon and file for divorce, the court will appoint a forensic auditor to review the entire contents of that Delaware entity.”
“Your compliance officer at your investment firm will receive a formal subpoena for every account statement and margin call you executed over the last twenty-four months.”
“I am quite certain your managing partners would love to know that their senior risk manager engaged in unauthorized offshore entity transfers to conceal personal margin deficits from marital assets.”
Arthur dropped into the conference room chair as if his spine had turned to water, staring at the floor with his jaw hanging slack.
The arrogant, spreadsheets-obsessed dictator who had spent six years measuring my self-worth in five-dollar grocery increments was completely gone, replaced by a terrified man whose entire professional career was dangling by a thread.
“What do you want?” he croaked, staring at his shoes.
“Here are my terms,” I said, sliding a second document across the table—a formal, attorney-drafted postnuptial financial stipulation.
“First: my salary remains in my own credit union account permanently. You will never see another penny of my paycheck, nor will you have access to my bank statements.”
“Second: you will wire two thousand dollars into my mother’s personal checking account by noon today for her medical care, accompanied by a handwritten letter apologizing for your unconscionable delay.”
“Third: you will assume full, exclusive legal responsibility for the mortgage, property taxes, structural insurance, and children’s private schooling out of your own income.”
“Fourth: you will deposit eight hundred dollars on the first of every month into a dedicated grocery fund managed entirely by me, with zero auditing rights on your part.”
“And finally: if you ever utter the words ‘discretionary leakages’ or criticize what I purchase for this household again, this entire folder goes directly to the managing partners of your firm and the Cuyahoga County Domestic Relations Court.”
Arthur stared at the terms, his Adam’s apple bobbing violently as he swallowed his own bile.
He picked up my cheap blue plastic pen, signed his full legal name on the three signature lines, and slid the papers back across the table without uttering a single syllable of protest.
By eleven o’clock that morning, a notification pinged on my phone showing a wire confirmation of two thousand dollars arriving in my mother’s account in Pennsylvania.
By two o’clock, the mortgage payment cleared through Arthur’s personal investment reserves, accompanied by the substantial penalty fee he had brought upon himself.
When I arrived home from school that afternoon, Arthur was standing in the kitchen in his shirtsleeves, silently scrubbing the stainless-steel pots with intense, desperate concentration.
On the counter sat three giant wooden crates from the local upscale organic market, overflowing with prime ribeye steaks, artisanal breads, ripe avocados, gourmet cheeses, and four massive cartons of plump, pristine raspberries.
Leo was sitting at the counter, blissfully chewing on a warm sourdough roll, while Chloe was happily stacking berries onto her fingertips like little red crowns.
Chloe looked up as I walked through the door, pointed at the mountain of fruit on the island, and gave me a dazzling, gap-toothed smile.
“Look, Mommy! Daddy went to the store and he didn’t even ask anybody for permission!”
I walked over to the kitchen island, picked up the largest raspberry from the bowl, and looked straight at Arthur, whose eyes immediately dropped back down toward the soapy bubbles in the sink.
I popped the berry into my mouth, savoring the cool, sweet burst of flavor, and leaned against the counter with absolute, unshakeable peace.
“Good job, Arthur,” I murmured gently. “It turns out your resource allocation skills aren’t entirely hopeless after all.”